Medicare looks simple until you try to apply it to your own life. As Medicare broker Dawn Cherry put it on The Voice of Aging: “For every answer, there’s a but.”
Below are answers to the questions we hear most often. This is general education, not advice about your specific plan. Your doctors, prescriptions, work situation, and budget all shape the right choice, so talk with a licensed Medicare professional about your own situation.
Figures below are for 2026 and usually change each year.
When should I start preparing for Medicare?
Earlier than most people think. Your Initial Enrollment Period is seven months long. It starts three months before the month you turn 65 and ends three months after it. Dawn Cherry recommends starting the planning conversation about six months before your 65th birthday. That gives you time to sort out Social Security, employer coverage, and your doctors and prescriptions before any deadline arrives.
Will I be signed up for Medicare automatically?
Sometimes. If you’re getting Social Security retirement or disability benefits at least four months before you turn 65, you’ll usually be enrolled in Part A and Part B automatically. Your card comes in a welcome package about three months before coverage starts. If you’re not collecting Social Security yet, you’ll generally need to sign up yourself.
What is Medicare Part A?
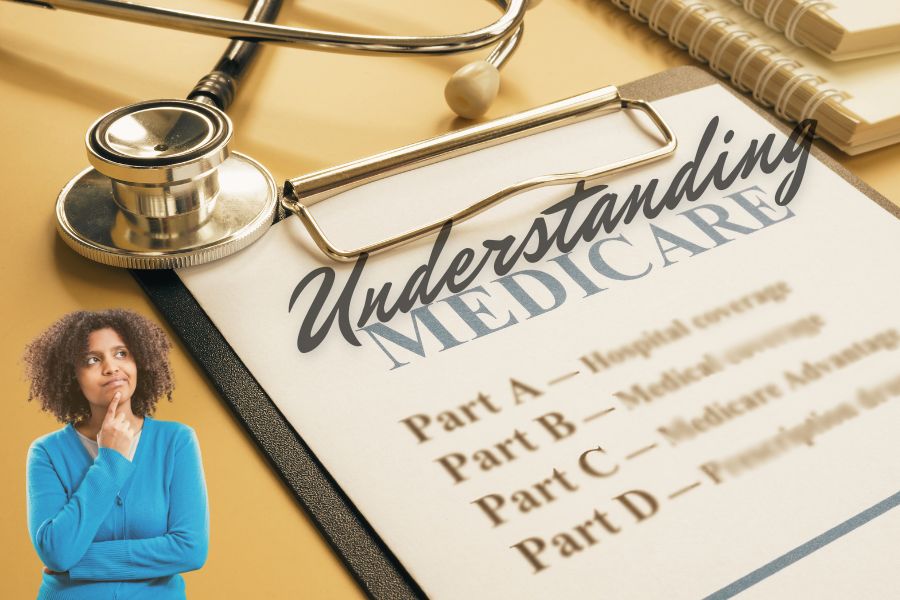
Part A is hospital insurance. It helps cover inpatient hospital care, skilled nursing facility care, hospice, and some home health care. Most people pay no Part A premium if they or a spouse worked and paid Medicare taxes for about 10 years (40 quarters). You do pay a deductible if you’re admitted: $1,736 per benefit period in 2026.
One important “but”: you have to be formally admitted as an inpatient. Time spent “under observation” doesn’t count as an inpatient stay, even overnight. That matters, because Medicare generally covers a skilled nursing facility stay only after a medically necessary inpatient hospital stay of at least three days in a row.
What is Medicare Part B?
Part B is medical insurance: doctor visits, outpatient care, preventive services, lab work and imaging, emergency and ambulance services, and medical equipment like wheelchairs. In 2026 the standard Part B premium is $202.90 a monthand the annual deductible is $283. After that, you generally pay 20% of the Medicare-approved amount. Original Medicare has no yearly limit on what you pay out of pocket.
People with higher incomes pay more for Parts B and D. This is called IRMAA. In 2026 it starts above $109,000 for individual tax filers and $218,000 for joint filers, based on your tax return from two years earlier.
What is Medicare Part C (Medicare Advantage)?
Medicare Advantage is an alternative to Original Medicare, offered by private insurance companies that Medicare approves. Plans must cover the medically necessary services Original Medicare covers. Most include drug coverage, and many offer extras like some dental, vision, and hearing benefits. Plans have a yearly out-of-pocket limit, but they usually use provider networks and may require prior approval for some services. Benefits and costs vary widely from plan to plan.
What is Medicare Part D?
Part D is prescription drug coverage. You can get it through a stand-alone drug plan alongside Original Medicare, or as part of a Medicare Advantage plan. In 2026 no plan can have a deductible above $615, and out-of-pocket spending on covered drugs is capped at $2,100 for the year. Covered insulin costs no more than $35 for a one-month supply.
What’s the difference between Original Medicare and Medicare Advantage?
Original Medicare (Parts A and B) lets you see any doctor or hospital in the U.S. that takes Medicare, usually without referrals. But it has no yearly out-of-pocket cap, and you add drug coverage separately. Medicare Advantage bundles coverage through a private plan with a yearly out-of-pocket limit, often with extras, but usually within a network. Neither is “best” for everyone. It depends on your doctors, prescriptions, health needs, travel, and budget.
What is Medigap?
Medigap (also called a Medicare Supplement) is extra insurance from a private company that helps pay your share of costs in Original Medicare, like the 20% coinsurance. Policies are standardized by letter, and they come with their own monthly premium. You can’t use Medigap with a Medicare Advantage plan. Timing matters: if you don’t buy a Medigap policy within six months of first having both Part A and Part B, you may not be able to buy one later, or it may cost more.

Can I keep working after 65 and use my employer insurance?
Often, yes. If you or your spouse are still working and covered by an employer plan based on that current job, you may be able to delay Part B and sign up later without a penalty. Employer size matters. With fewer than 20 employees, Medicare usually pays first, and many small-employer plans require you to enroll in Parts A and B. COBRA and retiree coverage don’t count as coverage from current employment. Check with your employer’s plan and a Medicare professional before you decide.
What happens if I miss Medicare enrollment?
You may face a gap in coverage and a late enrollment penalty:
- Part B: 10% added to your premium for each full 12-month period you could have had Part B but didn’t. It usually lasts as long as you have Part B.
- Part D: if you go 63 days or more without Part D or other creditable drug coverage after your enrollment period ends, you’ll pay 1% of the national base premium ($38.99 in 2026) for each month you went without, for as long as you have Medicare drug coverage.
Can my Medicare plan change every year?
Yes. Medicare Advantage and Part D plans can change their premiums, copays, covered drugs (formularies), and networks each year. That’s why it’s worth reviewing your coverage every fall, even if nothing about you has changed.
When can I change my plan?
- Open Enrollment:October 15 – December 7. Join, switch, or drop a Medicare Advantage or drug plan, or move between Original Medicare and Medicare Advantage. Changes take effect January 1.
- Medicare Advantage Open Enrollment:January 1 – March 31, if you’re already in a Medicare Advantage plan. You can make one change: switch to another Advantage plan or go back to Original Medicare.
- New to Medicare Advantage? You also get a one-time chance to change within your first three months of having both Part A and Part B.
Can my doctor leave my Medicare Advantage network?
Yes. Providers can leave a plan’s network at any time, and plans can add or remove providers during the year. Plans are expected to give you at least 30 days’ notice when a regular provider leaves. It’s a good habit to confirm your doctor is still in network when you book appointments.
Does Medicare cover prescription drugs?
Original Medicare covers very few outpatient prescriptions. For most medications you need Part D coverage, either a stand-alone drug plan or a Medicare Advantage plan that includes drugs.
Does Medicare cover nursing home care?
Not long-term care. Medicare may cover a short-term stay in a skilled nursing facility after a qualifying three-day inpatient hospital stay, for up to 100 days per benefit period, with daily coinsurance after day 20 ($217 a day in 2026). But Medicare, and most Medigap policies, don’t pay for long-term or custodial care in a nursing home.
Does Medicare cover me when I travel?
Within the U.S., Original Medicare works with any provider that accepts Medicare. Medicare Advantage coverage away from home depends on your plan’s network. Outside the U.S., Medicare usually doesn’t cover care, with rare exceptions. Some Medigap policies cover foreign travel emergencies, and some Advantage plans offer emergency travel benefits. Medicare drug plans don’t cover prescriptions bought outside the U.S. If you travel, ask about it before you choose a plan.
What should I bring to a Medicare appointment?
- Your medication list: name, dosage, and how often, or the bottles themselves
- Your doctors’ names, medical groups, and locations (business cards work well)
- Your work and coverage details: employer plan, Social Security status
- Any upcoming care: planned surgeries, therapy, or new diagnoses
- What matters most to you: travel, dental and vision, and your monthly budget
How can adult children help a parent with Medicare?
Start before there’s a crisis. Know which coverage your parent has and who their Medicare advisor is. Keep an up-to-date medication and doctor list. Watch the mail for plan notices, which often have deadlines. Make sure the right legal authority, like a power of attorney, is in place so you can help when it’s needed.
Need help sorting through your options?
Medicare decisions are easier when you don’t make them alone. Listen to our full conversation with Medicare broker Dawn Cherry on The Voice of Aging, or contact Aging Solutions to talk through the bigger picture of planning ahead: agingsolutionsnw.com.
This article is general education, not individual insurance advice. Medicare costs and rules change each year. Figures reflect 2026 information from Medicare.gov and CMS.gov, accessed September 23, 2026.
